Toyota Mirai Insurance Rates
Enter your zip code below to view companies that have cheap auto insurance rates.
Michelle Robbins
Licensed Insurance Agent
Michelle Robbins has been a licensed insurance agent for over 13 years. Her career began in the real estate industry, supporting local realtors with Title Insurance. After several years, Michelle shifted to real estate home warranty insurance, where she managed a territory of over 100 miles of real estate professionals. Later, Agent Robbins obtained more licensing and experience serving families a...
Licensed Insurance Agent
UPDATED: Jun 2, 2024
It’s all about you. We want to help you make the right coverage choices.
Advertiser Disclosure: We strive to help you make confident car insurance decisions. Comparison shopping should be easy. We are not affiliated with any one car insurance provider and cannot guarantee quotes from any single provider.
Our insurance industry partnerships don’t influence our content. Our opinions are our own. To compare quotes from many different companies please enter your ZIP code on this page to use the free quote tool. The more quotes you compare, the more chances to save.
Editorial Guidelines: We are a free online resource for anyone interested in learning more about auto insurance. Our goal is to be an objective, third-party resource for everything auto insurance related. We update our site regularly, and all content is reviewed by auto insurance experts.
U.S. average insurance rates for a Toyota Mirai are $1,820 a year with full coverage. Comprehensive insurance costs on average $388, collision costs $822, and liability coverage is $452. Liability-only coverage costs around $504 a year, with high-risk coverage costing $3,980 or more. Teen drivers pay the highest rates at $6,678 a year or more.
Average premium for full coverage: $1,820
Price estimates by individual coverage:
Full coverage includes $500 policy deductibles, 30/60 liability limits, and includes medical and uninsured motorist coverage. Estimates are averaged for all U.S. states and for different Mirai trim levels.
Price Range from Low to High
Using a 40-year-old driver as an example, Toyota Mirai insurance prices go from as low as $504 for just liability coverage to a much higher rate of $3,980 for a driver required to buy high-risk insurance.
Geographic Price Range
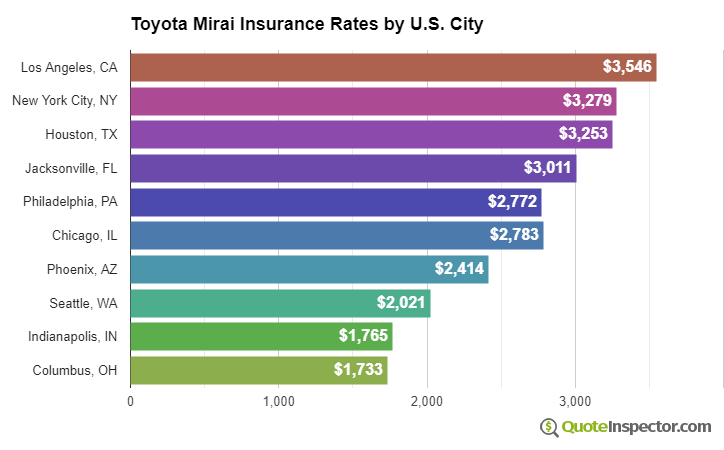
Choosing to live in a large city has a large influence on auto insurance rates. Rural areas have a lower frequency of collision claims than larger metro areas.
The price range example below illustrates how rural and urban location affects car insurance rates.
The ranges above demonstrate why anyone shopping for car insurance should compare rates quotes based on a specific location and risk profile, rather than using price averages.
Use the form below to get customized rates for your location.
Enter your zip code below to view companies based on your location that have cheap auto insurance rates.
Detailed Rate Analysis
The chart below details estimated Toyota Mirai insurance rates for different risk profiles and scenarios.
- The lowest rate with discounts is $1,009
- Raising to $1,000 deductibles will save around $274 annually
- The average rate for the average middle-age driver with $500 deductibles is $1,820
- Choosing more expensive low deductibles will cost an extra $538 each year
- Unlucky drivers with multiple violations and an at-fault accident could pay upwards of $3,980 or more
- The price for full coverage for a teenage driver with full coverage may cost $6,678
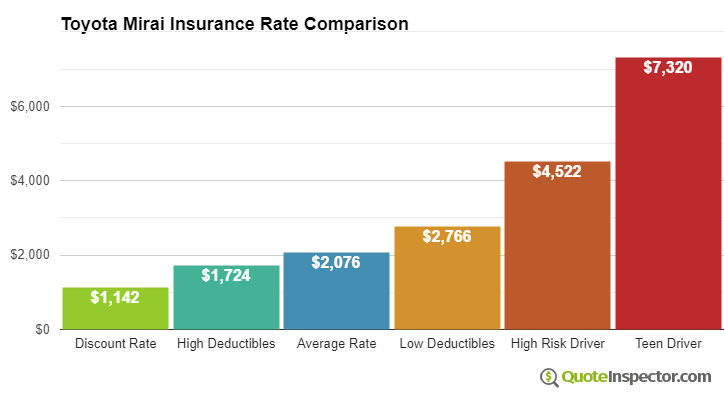
Auto insurance prices for a Toyota Mirai are also quite variable based on your driving record, the trim level and model year, and policy deductibles and limits.
An older driver with a good driving record and high deductibles may only pay around $1,700 every 12 months on average for full coverage. Prices are highest for teenage drivers, where even good drivers will have to pay upwards of $6,600 a year. View Rates by Age
The state you live in also has a big influence on Toyota Mirai insurance rates. A middle-age driver might find prices as low as $1,310 a year in states like New Hampshire, Ohio, and Utah, or as much as $2,460 on average in Florida, Michigan, and New York.
| State | Premium | Compared to U.S. Avg | Percent Difference |
|---|---|---|---|
| Alabama | $1,646 | -$174 | -9.6% |
| Alaska | $1,394 | -$426 | -23.4% |
| Arizona | $1,510 | -$310 | -17.0% |
| Arkansas | $1,820 | -$0 | 0.0% |
| California | $2,074 | $254 | 14.0% |
| Colorado | $1,738 | -$82 | -4.5% |
| Connecticut | $1,872 | $52 | 2.9% |
| Delaware | $2,058 | $238 | 13.1% |
| Florida | $2,276 | $456 | 25.1% |
| Georgia | $1,680 | -$140 | -7.7% |
| Hawaii | $1,306 | -$514 | -28.2% |
| Idaho | $1,232 | -$588 | -32.3% |
| Illinois | $1,356 | -$464 | -25.5% |
| Indiana | $1,370 | -$450 | -24.7% |
| Iowa | $1,228 | -$592 | -32.5% |
| Kansas | $1,730 | -$90 | -4.9% |
| Kentucky | $2,482 | $662 | 36.4% |
| Louisiana | $2,694 | $874 | 48.0% |
| Maine | $1,122 | -$698 | -38.4% |
| Maryland | $1,500 | -$320 | -17.6% |
| Massachusetts | $1,456 | -$364 | -20.0% |
| Michigan | $3,160 | $1,340 | 73.6% |
| Minnesota | $1,522 | -$298 | -16.4% |
| Mississippi | $2,180 | $360 | 19.8% |
| Missouri | $1,614 | -$206 | -11.3% |
| Montana | $1,954 | $134 | 7.4% |
| Nebraska | $1,436 | -$384 | -21.1% |
| Nevada | $2,182 | $362 | 19.9% |
| New Hampshire | $1,312 | -$508 | -27.9% |
| New Jersey | $2,034 | $214 | 11.8% |
| New Mexico | $1,612 | -$208 | -11.4% |
| New York | $1,916 | $96 | 5.3% |
| North Carolina | $1,048 | -$772 | -42.4% |
| North Dakota | $1,490 | -$330 | -18.1% |
| Ohio | $1,258 | -$562 | -30.9% |
| Oklahoma | $1,868 | $48 | 2.6% |
| Oregon | $1,666 | -$154 | -8.5% |
| Pennsylvania | $1,736 | -$84 | -4.6% |
| Rhode Island | $2,426 | $606 | 33.3% |
| South Carolina | $1,646 | -$174 | -9.6% |
| South Dakota | $1,534 | -$286 | -15.7% |
| Tennessee | $1,592 | -$228 | -12.5% |
| Texas | $2,192 | $372 | 20.4% |
| Utah | $1,346 | -$474 | -26.0% |
| Vermont | $1,244 | -$576 | -31.6% |
| Virginia | $1,090 | -$730 | -40.1% |
| Washington | $1,404 | -$416 | -22.9% |
| West Virginia | $1,668 | -$152 | -8.4% |
| Wisconsin | $1,260 | -$560 | -30.8% |
| Wyoming | $1,620 | -$200 | -11.0% |
Choosing high deductibles can reduce prices by up to $820 a year, while increasing your policy's liability limits will cost you more. Moving from a 50/100 limit to a 250/500 limit will increase prices by as much as $407 extra every year. View Rates by Deductible or Liability Limit
If you have some driving violations or tend to cause accidents, you may be forking out at a minimum $2,200 to $3,000 in extra premium each year, depending on your age. High-risk driver insurance is expensive and can cost around 45% to 135% more than average. View High Risk Driver Rates
Since prices can be so different, the best way to find out exactly what you will pay is to compare prices and see how they stack up. Every auto insurance company uses a different rate calculation, and quoted prices may be quite different from one company to the next.
| Model Year | Comprehensive | Collision | Liability | Total Premium |
|---|---|---|---|---|
| 2024 Toyota Mirai | $458 | $982 | $398 | $1,996 |
| 2023 Toyota Mirai | $442 | $958 | $416 | $1,974 |
| 2022 Toyota Mirai | $426 | $918 | $430 | $1,932 |
| 2021 Toyota Mirai | $402 | $886 | $442 | $1,888 |
| 2020 Toyota Mirai | $388 | $822 | $452 | $1,820 |
| 2019 Toyota Mirai | $372 | $774 | $456 | $1,760 |
| 2018 Toyota Mirai | $356 | $694 | $460 | $1,668 |
| 2017 Toyota Mirai | $334 | $638 | $460 | $1,590 |
Rates are averaged for all Toyota Mirai models and trim levels. Rates assume a 40-year-old male driver, full coverage with $500 deductibles, and a clean driving record.
How to Find More Affordable Toyota Mirai Insurance
Getting lower rates on auto insurance consists of avoiding accidents and claims, having good credit, avoid buying unnecessary coverage, and taking advantage of discounts. Set aside time to shop around at every policy renewal by getting quotes from direct companies like Progressive and GEICO, and also from local insurance agents.
The points below are a summary of the data raised in the charts and tables above.
- Consumers who require increased liability limits will pay about $500 every year to raise from a low limit to 250/500 limits
- You may be able to save as much as $230 per year simply by shopping early and online
- Increasing physical damage deductibles can save around $800 each year
- Drivers under the age of 20 are charged the highest prices, costing up to $557 a month if they have full coverage
Rate Tables and Charts
Rates by Driver Age
| Driver Age | Premium |
|---|---|
| 16 | $6,678 |
| 20 | $4,250 |
| 30 | $1,912 |
| 40 | $1,820 |
| 50 | $1,660 |
| 60 | $1,630 |
Full coverage, $500 deductibles
Rates by Deductible
| Deductible | Premium |
|---|---|
| $100 | $2,358 |
| $250 | $2,106 |
| $500 | $1,820 |
| $1,000 | $1,546 |
Full coverage, driver age 40
Rates by Liability Limit
| Liability Limit | Premium |
|---|---|
| 30/60 | $1,820 |
| 50/100 | $1,910 |
| 100/300 | $2,023 |
| 250/500 | $2,317 |
| 100 CSL | $1,956 |
| 300 CSL | $2,204 |
| 500 CSL | $2,385 |
Full coverage, driver age 40
Rates for High Risk Drivers
| Age | Premium |
|---|---|
| 16 | $9,598 |
| 20 | $6,782 |
| 30 | $4,082 |
| 40 | $3,980 |
| 50 | $3,800 |
| 60 | $3,770 |
Full coverage, $500 deductibles, two speeding tickets, and one at-fault accident
If a financial responsibility filing is required, the additional charge below may also apply.
Potential Rate Discounts
If you qualify for discounts, you may save the amounts shown below.
| Discount | Savings |
|---|---|
| Multi-policy | $100 |
| Multi-vehicle | $98 |
| Homeowner | $26 |
| 5-yr Accident Free | $146 |
| 5-yr Claim Free | $121 |
| Paid in Full/EFT | $91 |
| Advance Quote | $96 |
| Online Quote | $133 |
| Total Discounts | $811 |
Discounts are estimated and may not be available from every company or in every state.
Compare Rates and Save
Find companies with the cheapest rates in your area